AUSTIN REAL ESTATE | OCTOBER 2026
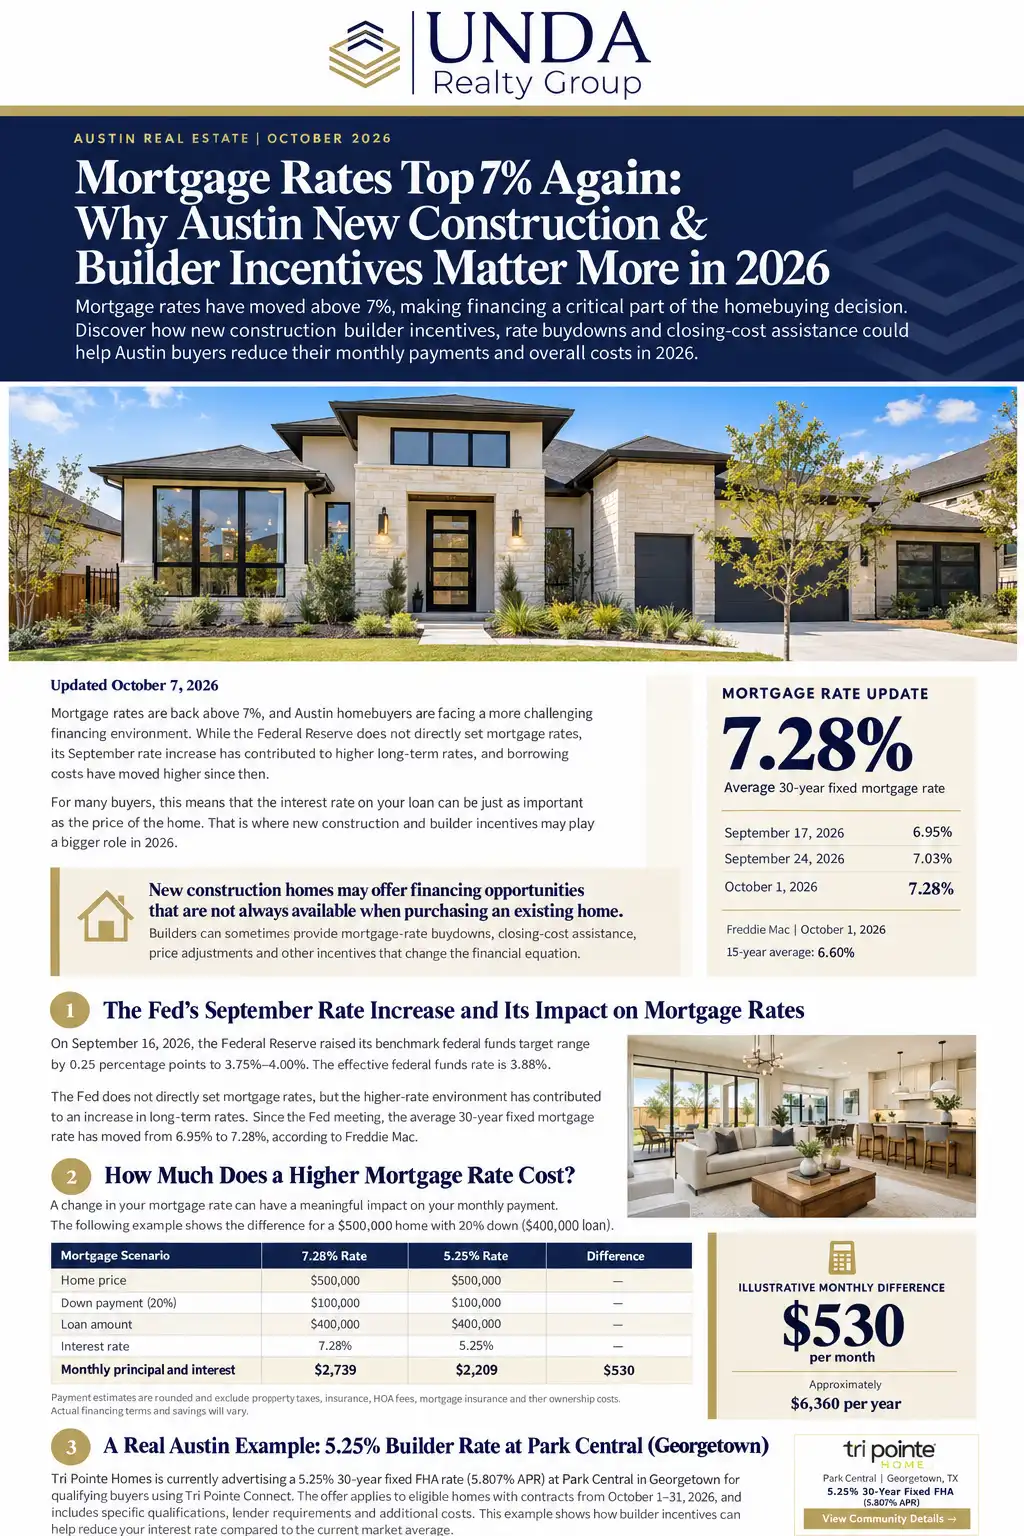
Mortgage Rates Are Above 7%: Why Austin New Construction & Builder Incentives Matter More in 2026
Mortgage rates have moved above 7%, making financing a critical part of the homebuying decision. Here is why builder rate buydowns, closing-cost assistance and other new-construction incentives deserve a closer look.
Updated October 7, 2026
Mortgage rates are back above 7%, and Austin-area buyers are facing a more challenging financing environment. On September 16, 2026, the Federal Reserve raised its federal funds target range by 0.25 percentage points to 3.75%–4.00%. The Fed does not directly set mortgage rates, but longer-term borrowing costs have also moved higher.
Freddie Mac reported that the average 30-year fixed mortgage rate reached 7.28% on October 1, 2026, up from 7.03% the prior week and 6.95% on September 17. For many buyers, that means the interest rate on the loan can be just as important as the price of the home.
New construction homes may offer financing opportunities that are not always available when purchasing an existing home.
Builders can sometimes provide mortgage-rate buydowns, closing-cost assistance, price adjustments and other incentives that change the financial equation.
1. The Fed’s September Rate Increase and Mortgage Rates
The Federal Reserve’s September increase brought its benchmark target range to 3.75%–4.00%. Mortgage rates are not directly set by the Fed; they respond to Treasury yields, inflation expectations, economic conditions, investor demand and lender pricing.
A 0.25-percentage-point Fed increase therefore does not automatically mean a 0.25-percentage-point increase in a 30-year mortgage rate.
MORTGAGE RATE UPDATE
7.28%
Average 30-year fixed mortgage rate
Freddie Mac | October 1, 2026
For Austin homebuyers, the practical question is not simply whether rates are rising or falling. The more important question is how the financing available on a particular property affects the monthly payment, cash required at closing and overall cost of ownership.
2. How Much Does a Higher Mortgage Rate Actually Cost?
Consider a buyer purchasing a $500,000 home with a 20% down payment and a $400,000, 30-year mortgage.
The comparison below illustrates why financing can materially change affordability.
| Scenario | 7.28% | 5.25% | Difference |
|---|---|---|---|
| Home price | $500,000 | $500,000 | — |
| Down payment | $100,000 | $100,000 | — |
| Loan amount | $400,000 | $400,000 | — |
| Monthly principal & interest | $2,737 | $2,209 | $528 |
ILLUSTRATIVE MONTHLY DIFFERENCE
$528/month
Approximately $6,336 per year
This example demonstrates why a lower mortgage rate can sometimes have a greater impact on monthly affordability than buyers expect from looking at the purchase price alone.
This is an illustrative mathematical comparison, not a mortgage quote or a claim that every buyer can obtain a 5.25% rate. Estimates exclude property taxes, homeowners insurance, HOA fees, mortgage insurance and other ownership costs. Actual financing terms will vary.
3. A Current Austin-Area Example: Tri Pointe Homes
As of October 7, Tri Pointe Homes is advertising incentives on eligible homes in several Austin-area communities.
At Park Central in Georgetown, for example, the builder is advertising a choice that includes up to $30,000 in closing-cost credit or a 5.25% FHA 30-year fixed rate (5.807% APR) for a specified qualifying scenario through Tri Pointe Connect.
The promotion requires an eligible home purchased at list price, financing through the affiliated lender, a qualifying contract during the promotional period and closing within the applicable deadline. The advertised scenario also assumes specific credit, down-payment, loan, points and fee conditions.
That means the promotional rate should not be interpreted as a rate available to every buyer. Instead, it demonstrates why buyers should investigate the financing packages available on individual new construction homes.
View Tri Pointe’s Park Central promotion →
4. Why New Construction Deserves More Attention When Mortgage Rates Rise
When mortgage rates are elevated, the best purchase is not necessarily the home with the lowest asking price.
Buyers should compare the complete financial package: purchase price, financing, closing costs, lot premiums, upgrades, property taxes, HOA expenses and available incentives.
PURCHASE PRICE + FINANCING + CLOSING COSTS + LOT PREMIUM + UPGRADES − BUILDER INCENTIVES
=
REAL COST OF THE HOME
According to the National Association of Home Builders’ September 2026 Housing Market Index survey, 66% of builders reported using sales incentives and 38% reported reducing home prices.
Those are national rather than Austin-specific statistics, but they illustrate how important incentives have become in the current new-home market.
For Austin buyers, this creates an important reason to compare new construction alongside resale homes rather than assuming that the resale property with the lower asking price automatically represents the better financial opportunity.
5. Which Builder Incentives Should Austin Buyers Compare?
Permanent Mortgage-Rate Buydowns
A permanent buydown reduces the mortgage note rate for the remaining term of the loan, assuming the mortgage is not refinanced or paid off. Buyers should compare the cost of obtaining the lower rate and any alternative builder incentives they may be giving up.
Temporary Mortgage-Rate Buydowns
Programs such as a 2-1 buydown can reduce payments during the first two years of the mortgage. Buyers should evaluate affordability based on the full payment after the temporary subsidy expires—not only the introductory payment.
Closing-Cost Credits
Builder credits may reduce the amount of cash required at closing or, when permitted, help pay eligible costs associated with financing. Loan-program limits and builder/lender conditions apply.
Quick Move-In & Inventory Incentives
Completed or nearly completed homes can sometimes carry stronger pricing or financing incentives because builders have capital tied up in inventory and may be motivated to close those homes sooner.
Lot, Upgrade & Design Incentives
Depending on the community and stage of construction, buyers may also find opportunities involving lot premiums, design selections, appliance packages or other upgrades. These should be evaluated together with price and financing rather than in isolation.
6. Should Austin Buyers Wait for Mortgage Rates to Fall?
Waiting for lower mortgage rates can seem attractive when monthly affordability is a major concern. The difficulty is that there is no reliable way to know when mortgage rates will fall—or where home prices and available inventory will be when they do.
Instead of making a purchase decision solely around a future rate forecast, buyers can compare the actual opportunities available today with their budget, expected ownership period and financial goals.
A new construction home with a strong builder financing package may deserve consideration alongside resale properties, particularly when the incentive materially reduces the monthly payment or cash required at closing.
That does not mean every new construction home is less expensive than a resale home. It means the financing package and incentives should be analyzed together with the purchase price.
7. Why Having Your Own Agent Matters When Buying New Construction
Walking into a builder’s model home can feel very different from touring a resale property. But one important fact remains:
The builder’s sales representative works for the builder. Your buyer’s agent represents you.
Having your own experienced buyer’s agent gives you dedicated representation of your interests. As your agent, we owe fiduciary duties to you under the applicable representation agreement and work to protect your interests throughout the transaction.
That includes applying our negotiating experience to the purchase price and overall builder package, evaluating incentives and financing options, reviewing lot premiums and upgrades, helping identify additional areas where the builder may have flexibility, coordinating inspections and guiding you through builder-specific contracts, timelines and decisions.
We can also help compare:
- Builder vs. builder
- Community vs. community
- Quick move-in inventory vs. building from a floor plan
- Advertised price vs. negotiated purchase package
- Rate buydown vs. closing-cost credit
- Builder lender vs. outside financing
- Lot premiums and location within the community
- Property taxes and HOA costs
- Included features vs. upgrades
- Future resale competition and marketability
And perhaps most importantly, we can help identify where the builder may have additional room to negotiate beyond the incentive advertised online.
Our objective is not simply to help you choose a new home. It is to represent you, negotiate on your behalf and help you make the strongest possible purchase decision.
Talk to us before your first builder visit.
Builder registration policies vary, and buyer representation may need to be established during your first visit or online registration. Contacting your agent before visiting the builder can help avoid potential representation issues.
Frequently Asked Questions
Did the Federal Reserve raise interest rates in September 2026?
Yes. On September 16, 2026, the Federal Reserve raised its federal funds target range by 0.25 percentage points to 3.75%–4.00%. The Federal Reserve does not directly set 30-year mortgage rates.
Are mortgage rates above 7%?
Freddie Mac’s October 1, 2026 survey reported an average 30-year fixed mortgage rate of 7.28%. Individual mortgage quotes vary based on lender, credit profile, loan program, down payment, points and other factors.
Can Austin builders offer mortgage rates below the market average?
Some builders advertise promotional financing through affiliated or preferred lenders for qualifying buyers and selected homes. Buyers should compare the note rate, APR, points and fees, loan type, lender requirements, closing deadlines and any alternative incentives before deciding which offer provides the greatest value.
Is a builder mortgage-rate buydown better than a price reduction?
It depends on the purchase price, loan amount, size and duration of the rate reduction, cost of the financing, expected ownership period and alternative incentives. A lower rate can sometimes produce greater monthly savings, while a price reduction lowers the acquisition price and loan balance.
Are new construction homes more affordable when mortgage rates are high?
They can be in certain situations. A builder financing incentive may reduce the monthly payment or cash required at closing, but buyers should compare purchase price, financing costs, property taxes, insurance, HOA fees, incentives and other ownership expenses before deciding.
Do I need a Realtor when buying new construction?
You are not required to use a Realtor when buying new construction, but having your own experienced buyer’s agent gives you something the builder’s sales team does not: dedicated representation of your interests.
The builder’s sales representative works for the builder. As your agent, we owe fiduciary duties to you under the applicable representation agreement and work to protect your interests throughout the transaction. That includes applying our negotiating experience to the purchase price and overall builder package, evaluating incentives and financing options, reviewing lot premiums and upgrades, helping identify additional areas where the builder may have flexibility, coordinating inspections and guiding you through builder-specific contracts, timelines and decisions.
Where can I find new construction homes with builder incentives near Austin?
New construction opportunities can be found throughout Greater Austin, including Austin, Buda, Kyle, Hutto, Georgetown, Leander, Liberty Hill, Dripping Springs and surrounding areas. Incentives change frequently by builder, community and individual home, so current written terms should always be confirmed.
UNDA REALTY GROUP • AUSTIN NEW CONSTRUCTION
Talk to Us Before You Visit the Builder.
We have experience working with buyers and major builders throughout Greater Austin.
We can help identify the right communities, compare current incentives, evaluate quick move-in inventory and financing options, and negotiate the overall purchase package—not just the advertised rate.
Compare Builder IncentivesBuyer Representation • Builder Negotiations • New Construction Expertise
Sources & Market Data
Federal Reserve — September 16, 2026 FOMC Statement: Federal Reserve
Freddie Mac — Primary Mortgage Market Survey: Freddie Mac PMMS
National Association of Home Builders — September 2026 Housing Market Index: NAHB
Tri Pointe Homes — Austin Area Promotions: Tri Pointe Homes
Disclaimer: This article is provided for general educational and real estate information only and does not constitute mortgage, financial, tax or legal advice. Mortgage rates, APRs, builder promotions, eligibility requirements, inventory and terms can change without notice. Buyers should verify current written terms for the specific property and financing program with the builder and lender. Payment examples are estimates and exclude property taxes, homeowners insurance, HOA fees, mortgage insurance and other costs. Equal Housing Opportunity.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).